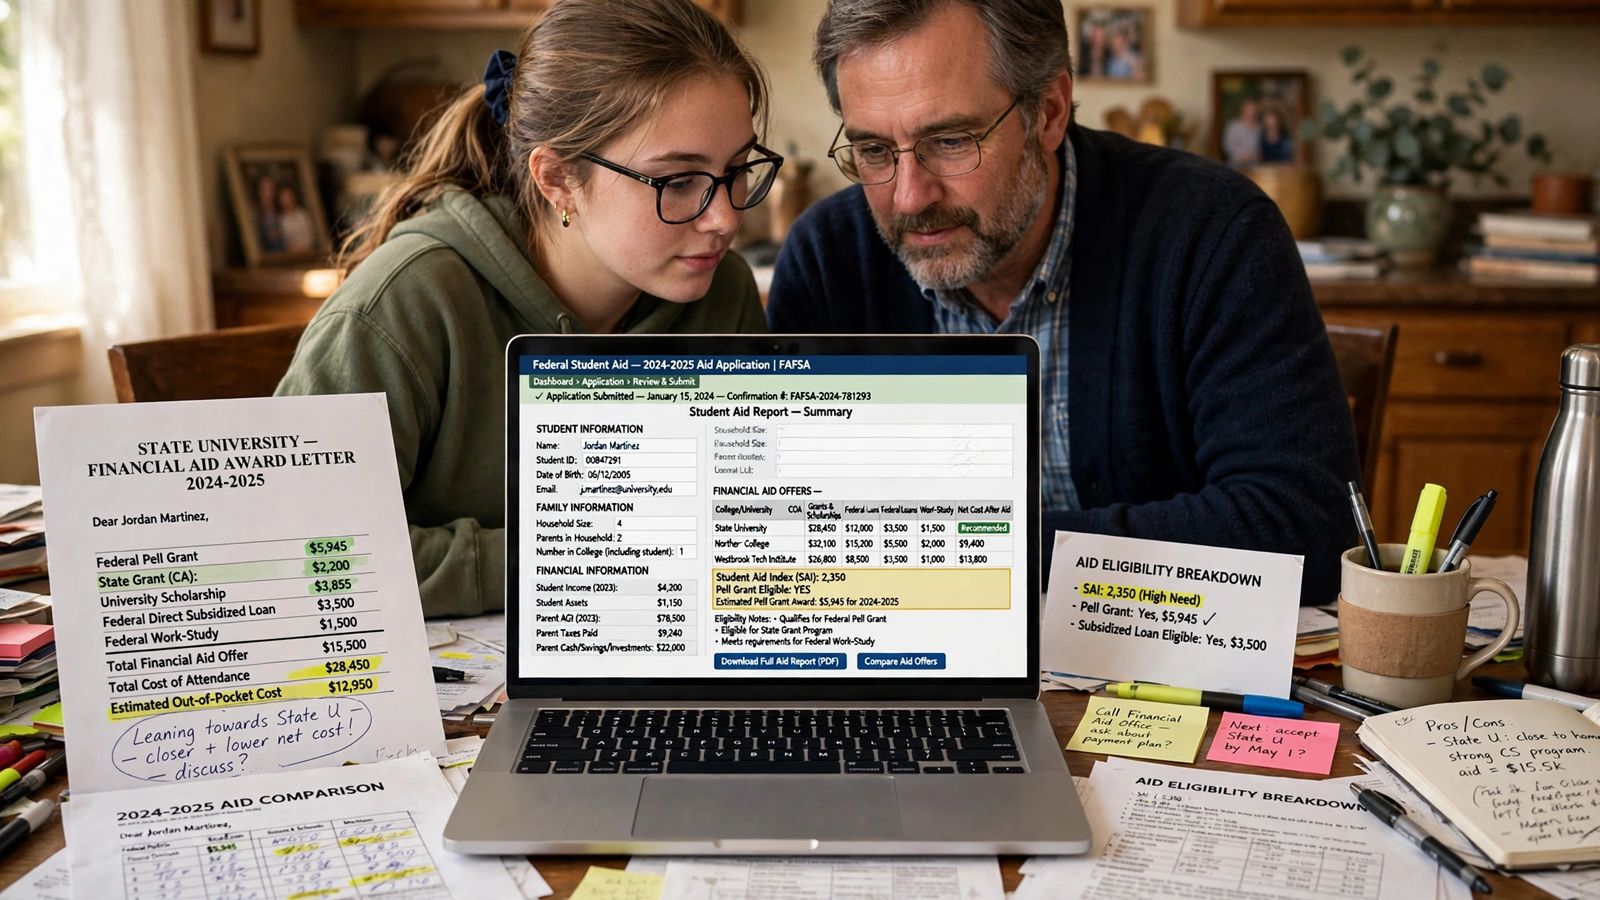
The student aid index (SAI) is a formula-based eligibility number that the US Department of Education calculates from the information you and your contributors provide on the Free Application for Federal Student Aid (FAFSA). It replaced the Expected Family Contribution (EFC) starting with the 2024–25 award year, under the FAFSA Simplification Act, and schools use it — together with their own cost of attendance — to work out how much financial need you have and how much need-based aid, including the Federal Pell Grant, you may be eligible for. It is an index, not a bill: Federal Student Aid states plainly that the SAI is not a dollar amount of aid you will receive, not the amount you or your family is expected to pay, and not your financial aid offer.
The SAI at a glance
| Fact | Detail |
|---|---|
| Where it comes from | The FAFSA form, calculated by the Department of Education |
| Range | −1,500 to 999,999 |
| Replaced | The Expected Family Contribution (EFC), from 2024–25 |
| Lower number means | Greater financial need |
| Higher number means | Less financial need |
| Used for | Pell Grant eligibility and need-based aid packaging |
| Where you see it | Estimated on the FAFSA confirmation page; official in the FAFSA Submission Summary |
| Same at every school? | Yes — the number is the same; your need changes because each school’s cost differs |
That last row is the one most families miss: the same student can show large need at one school and none at another, because the other side of the subtraction changes.
How schools use the SAI: the need formula
Federal Student Aid’s own one-page explanation of the SAI gives the formula schools work with. In its full form it is:
Cost of attendance (COA) − Student Aid Index (SAI) − Other financial assistance (OFA) = Financial need
Many guides shorten this to COA minus SAI. That is fine before any other aid exists, but it overstates what is left once a scholarship or grant has been awarded — remaining need shrinks as aid is added. Suppose your SAI is 5,000 and you have no other assistance yet: at a school with a COA of $30,000 your need is $25,000; at a school with a COA of $12,000 it is $7,000.
Need is a ceiling, not a promise: the most need-based aid — Pell Grant, Federal Supplemental Educational Opportunity Grant, subsidised Direct Loans, Federal Work-Study and need-based state or institutional grants — that a school may award you, with no requirement to meet the full ceiling. If your SAI is at or above a school’s COA, you show no need there; that closes need-based aid, but merit scholarships and non-need-based aid, including unsubsidised Direct Loans, do not depend on this subtraction.
A negative SAI needs one clarification several guides get wrong: it does not create aid above the cost of attendance. Total aid is still capped at the COA, and for Pell a negative SAI is treated as zero. The negative range simply identifies the students with the deepest need — useful when a school hands out limited campus-based funds.
SAI vs EFC: what actually changed
The SAI is not simply the EFC with a new name. The name changed partly because “Expected Family Contribution” was widely misread as the amount a family would actually be charged — but the FAFSA Simplification Act also rebuilt parts of the formula for 2024–25:
| EFC (through 2023–24) | SAI (from 2024–25) | |
|---|---|---|
| Lowest possible value | 0 | −1,500 |
| Number of family members in college | Parent contribution was divided among students in college | No division — the number in college no longer reduces the result |
| Allowance for state and other taxes | Included | Removed |
| Child support received | Counted as untaxed income | Reported on the asset side, not as income |
| Applicants not required to file a tax return | No automatic floor | Assigned an SAI of −1,500 in the cases the formula specifies |
Two deserve emphasis. The number-in-college change raised results for many families: two children at college used to split the parent contribution roughly in half each; now each is assessed on the full figure. The child support change usually works the other way — assets are assessed far more gently than income, so moving child support received to the asset side generally reduces its effect — while child support paid no longer appears as an allowance. These are formula changes, not rounding: an old EFC and a new SAI for the same family are not expected to match.
The farm and small business rule changed twice — check the year
This is the point on which the largest number of current guides are out of date, because the rule moved in both directions within three award years:
- Through 2023–24 (EFC): the net worth of a family farm and of a small family business was excluded.
- 2024–25 and 2025–26 (SAI as first introduced): that exclusion was removed. Businesses and farms counted as assets regardless of size — the FAFSA Simplification Act change, and the version most ranking pages still describe as current.
- From 2026–27: the exclusion is back for defined cases. Federal Student Aid’s 2026–27 FAFSA and Pell eligibility update, issued under the One Big Beautiful Bill Act (Pub. L. 119-21), states that the following are excluded from business and farm net worth and should not be reported as assets: a family-owned business with 100 or fewer full-time (or full-time equivalent) employees, a farm on which the family resides, and a family-owned and controlled commercial fishing business.
So “does a family business count?” depends on the award year, and on which side of the 100-employee and residence tests it falls. A business with more than 100 employees, and an investment farm the family does not live on, are not covered by the 2026–27 exclusion.
How the student aid index is calculated
The Department of Education publishes the full workings each year in chapter 3 of the Federal Student Aid Handbook’s Application and Verification Guide — the 2026–27 chapter is the current authority. In outline, there are three formulas: for dependent students (parent and student data), for independent students without dependents other than a spouse, and for independent students with dependents other than a spouse. All three follow the same logic — income first, assets second, allowances in between.
Income. The starting point is adjusted gross income (AGI), transferred directly from the IRS when contributors give the required consent, plus specified untaxed items — tax-exempt interest, untaxed IRA and pension distributions excluding rollovers, the foreign income exclusion, and deductible retirement contributions. The FAFSA uses prior-prior year income: the 2026–27 form reads the 2024 tax return; the 2027–28 form reads 2025. From total income the formula subtracts allowances — taxes paid, payroll taxes, an employment expense allowance, and the income protection allowance, which shelters a basic living-cost amount that rises with family size. For 2026–27, the parent allowance for a family of four is $44,880 (family of five: $52,950), and a dependent student’s own income is protected up to $11,770, then assessed at 50%.
Assets. Assets are reported as of the day the form is signed, not the tax year. What counts is cash, savings and checking balances, investments, and real estate other than the home you live in, subject to the farm and business rules above; primary-residence equity and qualified retirement balances do not count. The generations are treated very differently: parent assets are converted at 12% into the income side and assessed on a sliding scale of 22% to 47% — at most about 5.64 cents per dollar — while a dependent student’s own assets are assessed at a flat 20%. The same $10,000 moves the number far more in a student’s account than in a parent’s.
You do not need to run this yourself. Before filing, the official Federal Student Aid Estimator estimates your SAI and federal aid eligibility; after filing, the processed FAFSA gives the official figure — the estimate cannot bind a school.
How the SAI sets your Pell Grant
For the Pell Grant, the SAI is not just an input — in one of three routes it is almost the whole calculation. The Handbook describes three ways to qualify:
- Maximum Pell Grant — awarded on income grounds alone, regardless of the calculated SAI. For a dependent student: a parent not required to file a federal tax return, or parent AGI at or below 175% of the federal poverty guideline for family size and state — 225% for a single parent. (Independent students have their own thresholds in the same tables.)
- Minimum Pell Grant — also on income grounds, at higher thresholds: parent AGI at or below 275% of the guideline, or 325% for a single parent.
- Calculated Pell Grant — for students on neither income route, the award is the maximum Pell minus the SAI, a negative SAI treated as zero, rounded to the nearest $5.
The dollar figures are set per award year. For 2026–27 they are: maximum $7,395, minimum $740 (10% of the maximum) — the same headline figures as 2025–26. But a new rule arrived with 2026–27: an applicant with an SAI of 14,790 or higher — twice the maximum award — is ineligible for a Pell Grant (except students who qualify under the Special Rule for dependents of certain deceased service members and public safety officers). Before the separate income routes and enrolment intensity are applied, the 2026–27 map is:
| SAI (2026–27) | Calculated Pell outcome |
|---|---|
| −1,500 to 0 | Maximum Pell Grant, $7,395 |
| 1 to 6,655 | $7,395 minus SAI, down to the $740 minimum |
| 6,656 to 14,789 | No calculated Pell — but a minimum Pell may still come from the income route |
| 14,790 or above | No Pell Grant |
Two cautions: Pell is also limited by cost of attendance and enrolment intensity — a part-time award is a proportion of the full-time figure — and these dollars must not be carried into another year; the 2027–28 maximum had not been published alongside the figures above.
Where to find your SAI, and what to do if it looks wrong
You meet the number twice. An estimated SAI appears on your FAFSA confirmation page when you submit. The official SAI appears after processing in your FAFSA Submission Summary: sign in to StudentAid.gov, open the processed FAFSA for the correct award year from “My Activity,” and look at the Eligibility Overview tab — Federal Student Aid’s guide to the Submission Summary walks through each tab. The summary also shows estimated Pell eligibility; it is not an aid offer, which comes from each school after admission.
If the number looks wrong, separate the two ways it can be wrong. A factual error — a typo, a wrong figure, a school missing — is fixed by a correction from the Submission Summary. A changed reality is different: the formula rests on a two-year-old tax return, so a lost job, an income drop, or high medical costs since that year will not show. For that, ask your school’s financial aid office for a review — aid administrators can adjust individual elements through professional judgment, including, in a documented case, a second family member in college. Neither route changes the formula itself, and there is no appeal to Federal Student Aid against a correctly calculated SAI.
Frequently asked questions
Is the SAI the amount my family has to pay? No. It is not a bill, a required contribution, or a prediction of your final price. What you pay is a school’s cost of attendance minus the grants and scholarships it awards — a figure that can be well above or well below your SAI.
What is a good SAI? Lower, for aid purposes — need rises as the number falls. In 2026–27 terms, an SAI of 0 or below carries the maximum Pell Grant of $7,395, and 14,790 or above ends Pell eligibility. But “good” is relative to the school: a $30,000 SAI shows no need at a low-cost public college and substantial need at one costing $65,000. Unlike a test result — for which what is a good SAT score sets the national yardsticks — the SAI has no standalone pass mark.
Is there an average SAI? The Department of Education does not publish one, and any “average SAI” figure without a named official source should be treated as unverified. Judge where you sit against the year’s Pell thresholds above, not an average.
Does my SAI change from school to school? No. Every school that receives your FAFSA record receives the same SAI; your need changes because each school subtracts it from a different cost of attendance. A school may adjust it after a professional judgment review, and some schools use separate calculations for their own aid, but the federal number itself is one number.
Can I get aid with a high SAI? Yes — just not need-based aid beyond your calculated need. Merit scholarships, non-need-based grants, and unsubsidised loans do not require a low SAI, and at an expensive school even a comparatively high SAI can leave demonstrated need on the table. The grades side matters independently; how to calculate GPA covers the number colleges weigh alongside your file, and how many credits to graduate covers the degree the aid pays toward. Saving ahead changes the other side of the picture: money held in a parent-owned 529 plan counts as a parent asset in this same formula, so it is assessed far more gently than savings in the student’s own name.
Does the SAI change every year? Usually, yes. It is recalculated from each year’s FAFSA, so changes in income, assets, family size, dependency or marital status — and changes to the formula or its tables set in law — can move it either way. Last year’s number is not a forecast of this year’s.
This article is general information about the Student Aid Index, based on the Federal Student Aid and Department of Education sources linked above and checked in November 2026. Figures labelled 2026–27 apply to that award year only. Your school’s financial aid office is the final authority for your own aid offer.